
Buying Marine Insurance Special Surcharges for Asphalt Equipment in Hurricane Season
Contents |
[edit] Introduction
The sea transport of heavy construction machinery and asphalt production equipment involves a range of logistical and financial risks. These may include physical damage during loading and unloading, movement of cargo in transit, water ingress, corrosion, theft, delay and disruption caused by adverse weather.
Marine cargo insurance may be used to provide cover for equipment transported by sea, subject to the terms, conditions and exclusions of the policy. The level and cost of cover can vary according to factors including the nature and value of the cargo, the method of transport, the voyage, the ports involved, the packaging and securing arrangements, and the period during which the shipment takes place.
Where equipment is transported through areas affected by tropical cyclones or other severe weather, insurers may impose additional conditions, restrictions or premiums. These should be considered when estimating the total cost of procuring and transporting construction plant.
[edit] Marine cargo insurance and severe weather
The Atlantic hurricane season officially runs from 1 June to 30 November, although tropical cyclones can occur outside this period. The risk to cargo depends on the route, timing and actual weather conditions rather than the season alone.
Severe weather can affect maritime transport in several ways. High winds and heavy seas may increase the risk of cargo movement or damage, while storm warnings can result in vessels altering their routes or schedules. Ports may close temporarily, restrict operations or experience congestion following severe weather. These disruptions can extend transit times and increase the period during which equipment is exposed to handling and storage risks.
The terms used to describe weather-related insurance cover vary between insurers and policies. A policy should therefore be checked carefully to establish whether loss or damage caused by storms, heavy weather or other named perils is covered, and whether additional conditions or premiums apply.
Additional costs may also arise from freight contracts and port operations. These can include charges associated with delays, storage, diversion or other disruption, although such costs are not necessarily covered by marine cargo insurance.
[edit] Equipment classification and insurance cover
The equipment being transported should be accurately described in insurance and shipping documentation. An asphalt production facility may consist of structural components, aggregate handling equipment, dryers, burners, mixing equipment, electrical systems and electronic controls. These components can have different vulnerabilities during transport.
Heavy structural components may be resistant to impact but remain vulnerable to corrosion, inadequate securing and handling damage. Electronic equipment, sensors and control systems may be more susceptible to moisture, condensation, vibration and shock. Appropriate packaging and transport arrangements should reflect these differences.
Marine cargo policies commonly use the Institute Cargo Clauses or other equivalent policy conditions to define the scope of cover. Institute Cargo Clauses (A), (B) and (C) provide different levels of cover and contain exclusions and conditions. Institute Cargo Clauses (A) are often described as providing the widest standard cover, but they do not cover every possible cause of loss or damage. The precise scope of cover depends on the policy wording and any additional clauses or endorsements.
Cargo declarations should normally include:
- A clear description of each item or component.
- The declared or insured value.
- The method of packaging.
- The method of transport and stowage.
- Details of any unusual handling or lifting requirements.
- Information about sensitive or high-value components.
An accurate declaration can help ensure that the cargo is properly insured and that the policy reflects the nature of the equipment being transported.
[edit] Packaging, stowage and securing
The method used to transport heavy construction equipment can significantly affect its exposure to risk. Smaller components may be transported in enclosed containers, while oversized machinery and structural sections may require flat-rack containers, open-top containers, roll-on/roll-off transport or breakbulk shipping.
Equipment carried in open or partially exposed positions may be more vulnerable to sea water, salt spray and weather. Unprotected metal surfaces can corrode, while electrical and electronic equipment may be damaged by water ingress or condensation.
Cargo should be packaged and secured in accordance with the requirements of the carrier, applicable maritime regulations and the characteristics of the equipment. This may include the use of appropriate lifting points, blocking, bracing, lashing and protective coverings.
Particular attention may be required for:
- Electronic control panels and sensors.
- Motors and other electrical equipment.
- Machined surfaces and drive components.
- Equipment with exposed bearings or hydraulic connections.
- Components requiring specialist lifting or handling.
- Large items transported on flat racks or as breakbulk cargo.
Insurers may require evidence that the cargo has been appropriately packed and secured. Depending on the shipment and policy requirements, this may include photographs, inspection records or pre-shipment surveys.
[edit] Managing insurance costs and procurement risks
The cost of marine cargo insurance should be considered alongside the purchase price, freight, handling, customs charges and other transport costs. Insurance costs can vary according to the insured value and the perceived risk of the voyage.
Project programmes should allow for potential weather-related disruption where equipment is being transported through regions affected by seasonal storms. Where programme flexibility exists, the timing of a shipment may be considered alongside weather patterns, vessel availability and port conditions. However, avoiding a particular period does not remove the risk of severe weather.
Accurate cargo valuations are also important. Underinsurance may result in insufficient recovery following a loss, while declaring values that do not reflect the basis required by the policy may increase costs unnecessarily. The basis of valuation should be agreed with the insurer and may include additional costs such as freight and insurance, depending on the terms of the policy.
Before shipment, those responsible for procurement and logistics should establish:
- The scope of marine cargo cover and any relevant exclusions.
- Whether additional premiums, endorsements or conditions apply to the intended voyage.
- The insured value and basis of valuation for the equipment.
- The requirements for packaging, securing and stowage.
- Any survey or inspection requirements.
- The procedures and evidence required in the event of loss or damage.
- The extent to which delay, storage, diversion or other consequential costs are covered.
Marine cargo insurance should form part of a wider risk management process that considers the equipment, transport route, shipping arrangements, programme and contractual responsibilities.
[edit] Related articles on Designing Buildings
Featured articles
Check out some of the best features and news from Designing Buildings as well as key stories from around the web.
Your guide to The Construction Reset at UKCW Birmingham.
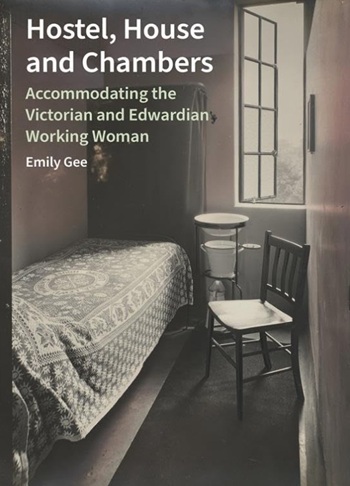
Accommodating the Victorian and Edwardian working woman. Book review.
Rethinking passive fire protection in design
PFP demands the same level of design rigour as structure or services.
38% of Gen Zs feel safe when a fire door is wedged open.
Stunning images from around the world
Shortlist for CIOB’s Art of Building photography competition.
Guidance for conversion of traditional pre-1919 stone buildings.
Industrial heritage in the Ruhr
A marked difference to the fate of industrial landscapes in the UK.
Communities will be able to build their own clean energy.
Why diversity and inclusion matters for SMEs
CIOB’s D&I Charter shows how practical changes can support long-term growth.
Cut electricity bills to power growth
Coalition sends joint letter to the Chancellor.

Gasholders: a history in pictures. Book review.
Recognition, influence and growth
SocEnv identifies three strategic pillars in new strategy to 2045.